The SBA’s two flagship loans answer different questions. A 7(a) loan is the flexible, general-purpose option, able to cover working capital, a business acquisition, equipment, debt refinancing, or owner-occupied real estate in a single loan. A 504 loan is the specialist: long-term, fixed-rate money for owner-occupied commercial real estate and heavy equipment, delivered through a bank and a Certified Development Company. Which one fits comes down to what you’re buying and whether you value flexibility or the lowest fixed rate.
Key takeaways
- The 7(a) is general-purpose (up to $5 million, one lender); the 504 is fixed-assets-only, real estate and heavy equipment, delivered through a bank plus a CDC.
- A 504 gives a long-term fixed rate on the SBA debenture; a 7(a) is usually variable, tied to the Prime Rate.
- The 504 caps only its SBA debenture at $5 million ($5.5 million for small manufacturers and energy projects), so total 504 project size can run above the 7(a)’s $5 million loan cap.
- A 504 can’t fund working capital, inventory, or a business purchase; when a deal mixes real estate with any of those, it’s a 7(a) job.
- Both require an SBA Form 413 and an unconditional personal guarantee from every owner of 20% or more.
- The 504 usually closes slower, because two lenders plus the CDC and the SBA all review it; the 7(a) is typically faster and simpler to structure.
What an SBA 7(a) loan is
The SBA 7(a) loan is the Small Business Administration’s primary general-purpose business loan. A single bank or SBA-approved lender underwrites, funds, and services the loan, and the SBA guarantees a portion of it, up to 85% on loans of $150,000 or less and 75% above that. One 7(a) loan can cover working capital, equipment, a business acquisition, debt refinancing, or owner-occupied real estate, up to a $5 million maximum.
Flexibility is the whole point of the 7(a). The SBA’s 7(a) program page lists eligible uses that span nearly every business need: buying or improving real estate, short- and long-term working capital, refinancing business debt, purchasing machinery and equipment, buying furniture and fixtures, and financing a full or partial change of ownership. Several of these are often combined in a single loan. That breadth is why lenders call it the SBA’s workhorse.
The trade-off is price. A 7(a) is almost always a variable-rate loan: a base rate, usually the Wall Street Journal Prime Rate, plus a lender spread, subject to SBA maximums. With Prime at 6.75% in early May 2026, the SBA cap on a loan over $250,000 was Prime plus 3.0% for a variable rate (9.75%) and Prime plus 5.0% fixed (11.75%), and a real-estate 7(a) floats with the market inside that ceiling. Maturities run up to 25 years for real estate and up to 10 years for equipment or working capital.
Collateral is where borrowers often feel the 7(a)’s reach. Under SOP 50 10 8, a 7(a) lender is expected to take available collateral to fully secure a larger loan, which can include a lien on your personal residence when the business assets don’t cover the balance. If you own the building your business operates from, a 7(a) can finance it, but the lender’s security interest tends to be broader than a 504’s. The specifics of the personal-side paperwork are in our SBA 7(a) personal financial statement requirements guide, and the wider document set for an owner-user deal sits in the business loan applications use case.
What an SBA 504 loan is
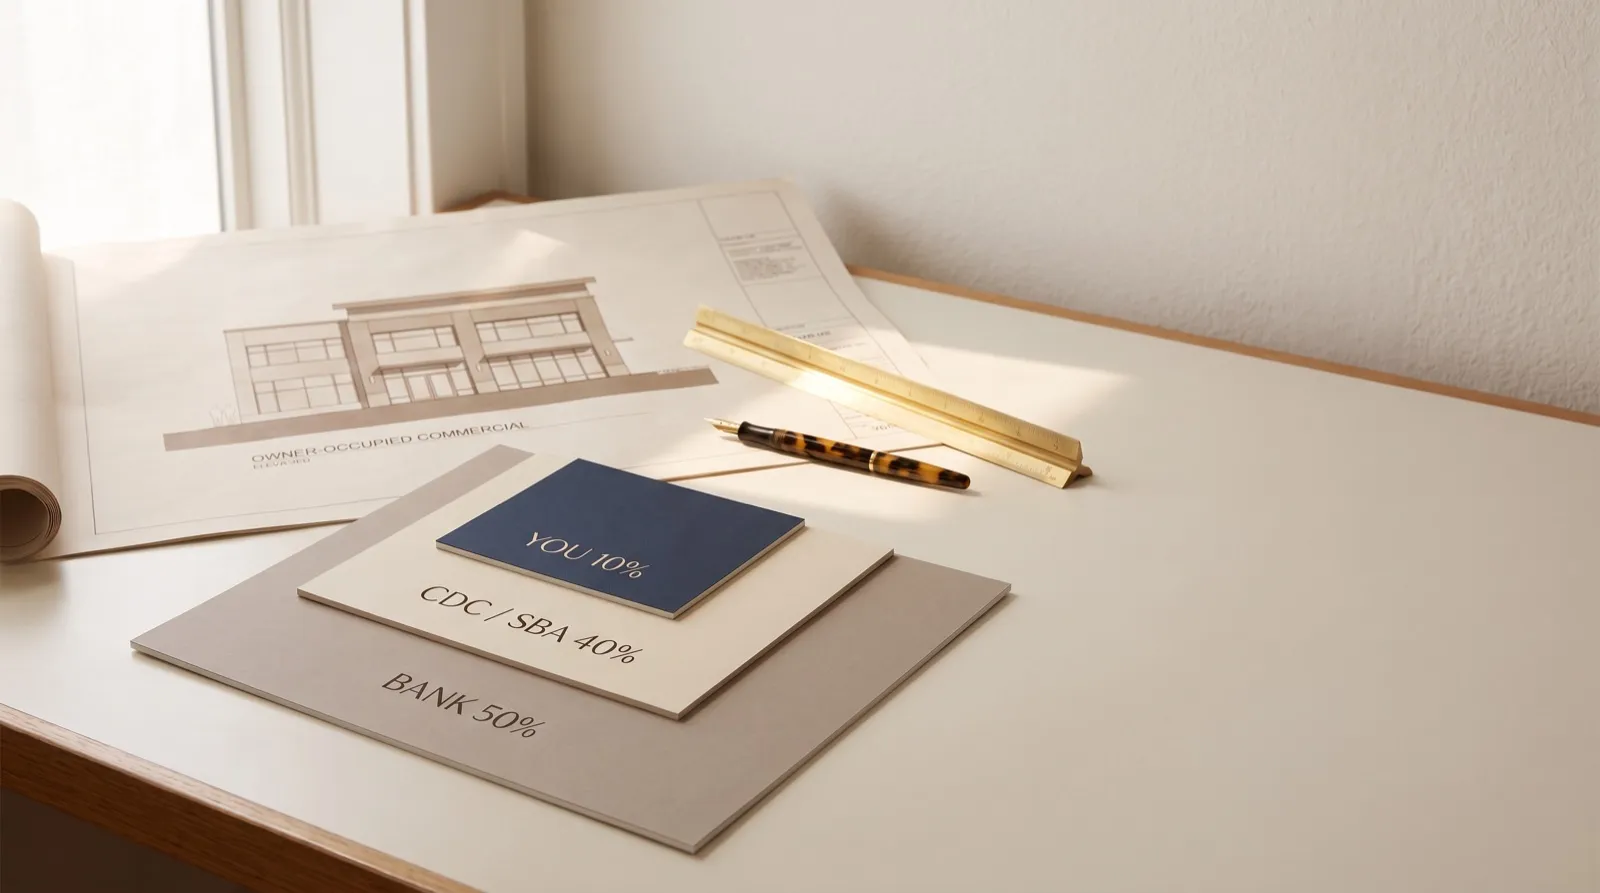
The SBA 504 loan is a fixed-asset financing program delivered through a Certified Development Company (CDC) alongside a conventional bank. A typical 504 uses a 50/40/10 structure: the bank lends about 50% in a first-lien position, the CDC lends about 40% through an SBA-guaranteed debenture at a long-term fixed rate, and the borrower contributes about 10% as equity. Proceeds are limited to fixed assets, owner-occupied commercial real estate and heavy equipment with a useful life of at least 10 years.
The 504’s structure is its defining feature. Instead of one loan, you get two: a first-lien bank loan for roughly half the project, and a second-lien SBA-backed debenture from the CDC for about 40%, as CDC Small Business Finance lays out. Because the debenture is pooled and sold in the capital markets, its rate is fixed for the full term. The SBA debenture is capped at $5 million for most projects and $5.5 million for small manufacturers and qualifying energy projects, per SBA debenture limits. The bank’s 50% first mortgage isn’t SBA-capped, so total 504 project size can climb well above the 7(a)’s $5 million ceiling.
Walter McLaughlin, who runs SBA lending at Banner Bank, frames the 504’s narrower scope as a feature rather than a limitation:
It’s more narrowly purposed than the 7(a), but has key interest rate and structural advantages.
That narrowness is worth taking literally.
The 504’s collateral posture is also lighter on the borrower. Its security is generally limited to the project being financed, so the lender typically doesn’t reach for a lien on your home the way a 7(a) lender might on a comparable loan. Debenture maturities come in 10-, 20-, and 25-year terms, matched to the economic life of the asset, and the 25-year option has been standard since 2018. For a building the business intends to hold, that combination of a long fixed rate and project-only collateral is the 504’s core appeal. The guarantee side of the paperwork is covered in our SBA 504 personal guarantee requirements post, and the broader investor workflow is in the commercial real estate investors use case.
SBA 7(a) vs. 504 — head to head
| Dimension | SBA 7(a) | SBA 504 |
|---|---|---|
| Best for | Working capital, acquisitions, mixed-use deals, flexible needs | Owner-occupied real estate and heavy equipment |
| Max SBA amount | $5M total loan | $5M debenture ($5.5M manufacturers/energy); total project can run higher |
| Structure | One lender, one loan | 50% bank + 40% CDC/SBA debenture + 10% borrower |
| Eligible uses | Almost any business purpose | Fixed assets only, no working capital, inventory, or business purchase |
| Interest rate | Usually variable, Prime + spread (SBA-capped) | Fixed on the SBA debenture; bank portion set separately |
| Down payment | ~10% on acquisitions | 10% standard; 15% new-or-special-purpose; 20% new-and-special-purpose |
| Maturities | Up to 25 yrs real estate, 10 yrs equipment/working capital | 10-, 20-, or 25-year debentures |
| Collateral | Lender takes available collateral, can include your home | Generally limited to the financed project |
| Closing speed | Faster, one underwrite | Slower, bank + CDC + SBA review |
The down-payment row rewards a closer look. On a 504, the standard 10% equity rises to 15% when the business is new or the property is special-purpose (a hotel, gas station, or restaurant, for example), and to 20% when both conditions hold. On a 7(a), SOP 50 10 8 sets a floor of 10% equity for a startup or a change of ownership. As the Whiteford law firm notes, a seller note counts toward that injection only if it sits on full standby for the life of the loan and covers no more than half of the required equity. SOP 50 10 8.1, for loans submitted from October 1, 2026, keeps both limits and counts minority-investor equity against the same half. Neither program is a no-money-down loan.
What each one costs in 2026
Rate is where the two programs separate most clearly, and in a higher-rate year the 504’s fixed debenture is its strongest card.
6.11%
Effective interest rate on a 25-year SBA 504 debenture as of the June 2026 funding cycle (20-year 6.16%, 10-year 5.88%), fixed for the life of the loan and inclusive of SBA, CDC, and servicing fees. Variable 7(a) rates floated higher against a 6.75% Prime.
Those 504 debenture rates are all-in: the published effective rate already bundles the SBA guaranty fee, the CDC fee, and the central servicing fee, so a borrower experiences one fixed payment on the SBA portion. A 7(a), by contrast, charges a one-time upfront guaranty fee on the guaranteed portion, scaled to loan size, and then floats with Prime. For a borrower who cares most about a low, predictable blended cost of capital on a building they’ll hold for a decade, the 504 math usually comes out ahead. For a borrower who wants flexibility, speed, or a single loan, the 7(a) premium buys something real.
One fee wrinkle is worth knowing if you manufacture anything, sell into the food supply chain, or operate in a rural area. For fiscal 2027 (loans approved from October 1, 2026 through September 30, 2027), the SBA waives the 504 upfront and annual service fees for manufacturers, certain food supply chain businesses, and rural businesses, at any loan size. On the 7(a) side, the same three groups pay a 0% upfront fee on loans of $700,000 or less. The fiscal 2026 waiver covered manufacturers only. The 504 waiver lowers the effective rate for qualifying borrowers, which is why the manufacturing debenture rows in the CDC’s rate table sit below the standard ones.
The two programs also run at very different scale, which tells you something about who uses each.
$7.8 billion
SBA 504 loans approved in FY2025 (about 6,750 loans, averaging roughly $1.15 million each), against 77,600 smaller-balance 7(a) loans totaling $37 billion. The 504 program skews toward larger, real-estate-heavy deals.
Source: U.S. Small Business Administration, FY2025 year-end lending totals
Build your personal financial statement in minutes
StatementsReady syncs bank balances read-only through Plaid, fills SBA Form 413, and exports a lender-ready PDF on demand.
- SBA Form 413 with every section filled
- Bank sync through Plaid, read-only
- 7 days free, no card
When an SBA 7(a) loan is the right call
- Your deal mixes real estate with anything else. Buying a building along with the business inside it, or needing working capital on top of the property, means the 504 can’t cover the whole thing. A 7(a) rolls it into one loan.
- You’re buying a business or a partner out. Acquisitions and partner buyouts are 7(a) territory; a 504 is barred from financing goodwill or the purchase itself.
- Speed matters. With one lender and one underwrite, a 7(a) generally closes faster than a 504’s stacked bank-plus-CDC-plus-SBA review, where the added parties lengthen processing.
- You want flexibility over the lowest rate. If the project doesn’t fit neatly into the fixed-asset box, the 7(a)’s general-purpose design is the reason it exists.
When an SBA 504 loan is the right call
- You’re buying or building owner-occupied real estate to hold. A long-term fixed rate on the SBA debenture is worth the most when you plan to own the property for years.
- You’re financing heavy equipment with a long life. Machinery with a useful life of 10 years or more fits the 504’s fixed-asset mandate cleanly.
- You want to protect your rate against where Prime might sit later. Locking the SBA debenture fixes the rate on about 40% of the project, and many banks fix their first mortgage too, so a 504 can shield most of the financing from the rate moves that reprice a variable 7(a).
- Your project runs above the 7(a) cap. Because only the SBA debenture is capped, a larger project can pair a bigger conventional first mortgage with the 504 and clear the $5 million 7(a) ceiling.
The honest framing is that most owner-users don’t have to force the choice. A borrower buying a building and nothing else usually lands on a 504 for the rate; a borrower buying a building plus a business, or one who needs to close in weeks, lands on a 7(a). Both respect the same underwriting bar, and both leave you a personally guaranteed loan.
When you need both, or a 7(a) that does it all
Some deals resist a clean split. Picture buying a manufacturing company together with the plant it operates in. The real estate qualifies for a 504, but the business acquisition and any working capital don’t, so a lender will often either run the whole thing as a single 7(a) or pair a 504 on the real estate with a 7(a) on the business.
The choice usually turns on how large the real-estate piece is relative to the rest and on how much the fixed-rate savings on the building outweigh the simplicity of one loan. A commercial mortgage broker who has closed both will size the two structures side by side before recommending one — you can compare the 7(a) and 504 monthly payment yourself in our SBA loan calculator. If your project also touches investment property rather than owner-occupied space, our DSCR vs. personal-income mortgage breakdown covers where SBA financing stops and investor financing begins, and you can pressure-test a property’s cash flow in the free DSCR calculator before you talk to a lender.
What both loans require from you
Whichever program you choose, the SBA asks the owners the same two things. Every owner of 20% or more of the applicant business has to complete SBA Form 413, the personal financial statement, and provide an unconditional personal guarantee on the loan. A married owner’s spouse generally completes a separate Form 413. The requirement is identical across 7(a) and 504 because both are underwritten to the same SOP 50 10 8 standards, and both real-estate transactions carry the same 51% owner-occupancy floor for an existing building (60% for new construction).
That Form 413 is the document most borrowers underestimate. It has to reconcile internally, tie to the tax returns and bank statements behind it, and be current when the lender finishes underwriting. The full section-by-section walkthrough is in our guide to filling out SBA Form 413, and if you’d rather start from a structured form than a blank PDF, the SBA Form 413 template mirrors the current layout. To confirm the net-worth figure a lender will read off the bottom of the form, our net worth calculator and the how to calculate net worth for an SBA loan walkthrough show the math the underwriter runs.
StatementsReady handles the tedious part here. Sync your accounts read-only through Plaid and the cash and securities that support your equity injection populate the statement directly; StatementsReady never sees your bank login and does not pull your credit. The features page lists what the tool handles, and more posts on both programs live in the SBA lending and commercial real estate archives.
Related reading
- SBA 7(a) personal financial statement requirements
- SBA 504 personal guarantee requirements
- How to fill out SBA Form 413, section by section
- More posts in the SBA lending and commercial real estate archives.
Choosing between a 7(a) and a 504 is really a question about the deal, not the borrower: fixed assets you’ll hold point one way, flexibility and speed point the other. Whichever you land on, the SBA asks every 20%-plus owner for the same personally guaranteed Form 413, so have a current personal financial statement ready before underwriting asks instead of rebuilding a spreadsheet the night before.
Skip the spreadsheet
A lender-ready personal financial statement from synced balances, in about 8 minutes.
- 7 days free
- No credit card
- PDF, SBA Form 413, Word, or Excel
Build your personal financial statement in minutes
StatementsReady syncs bank balances read-only through Plaid, fills SBA Form 413, and exports a lender-ready PDF on demand.
- SBA Form 413 with every section filled
- Bank sync through Plaid, read-only
- 7 days free, no card