Commercial Real Estate
What Is a Capital Stack? Layers, Order, and Cost
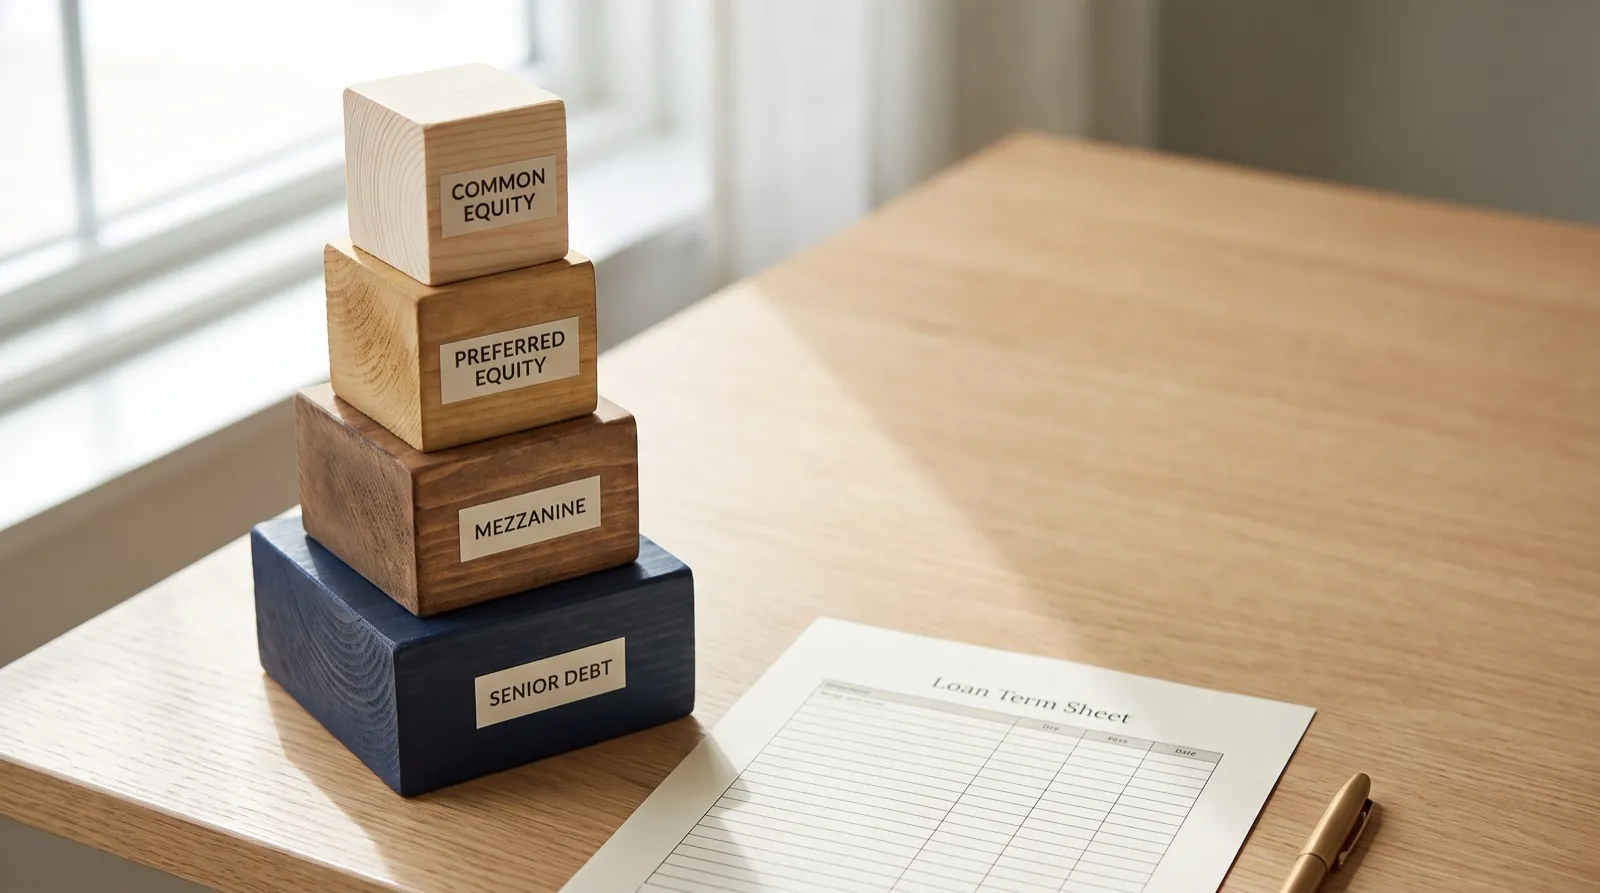
A capital stack is the layers of debt and equity funding a deal, ranked by repayment priority. Senior debt to common equity, and what each layer costs.
DSCR loans, multifamily acquisitions, REPE reporting, and personal financial statements for real estate investors and operators.
A capital stack is the layers of debt and equity funding a deal, ranked by repayment priority. Senior debt to common equity, and what each layer costs.
The loan-to-cost ratio is your loan divided by total project cost. It sets how much equity you bring to a construction or SBA 504 deal.
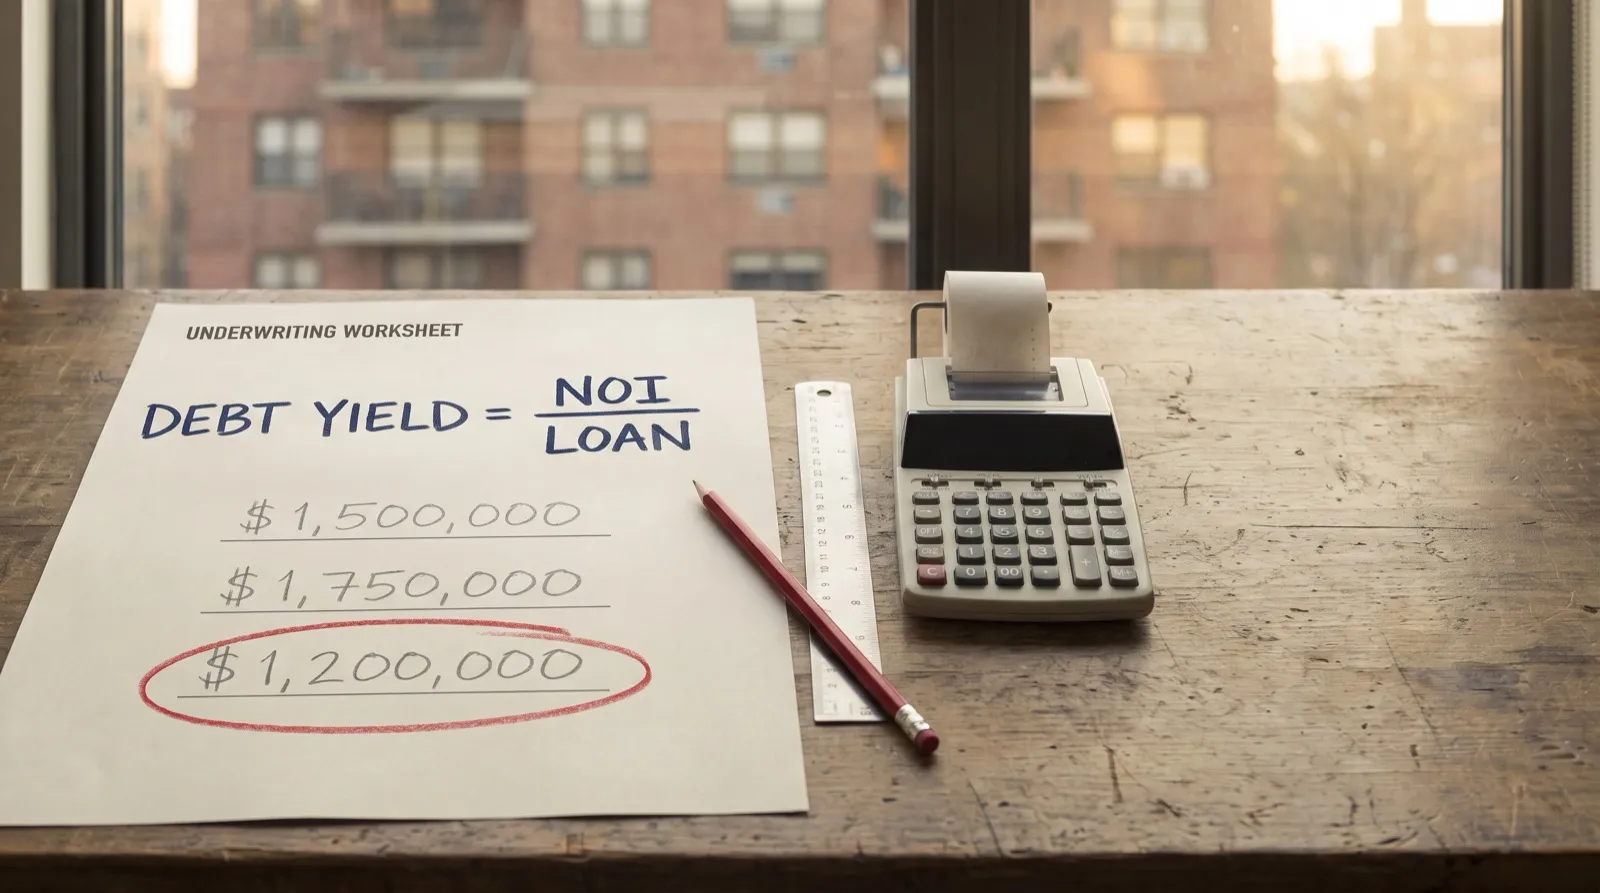
Debt yield is net operating income divided by the loan amount. On many commercial deals it caps the loan below what LTV and DSCR would allow.
A rent roll lists every unit, tenant, and rent at a property. Underwriters apply their own vacancy floor to it before they size your loan.
The 10 types of commercial real estate loans compared: bank, SBA 504/7(a), agency, CMBS, life company, DSCR, bridge, construction, and mezzanine.
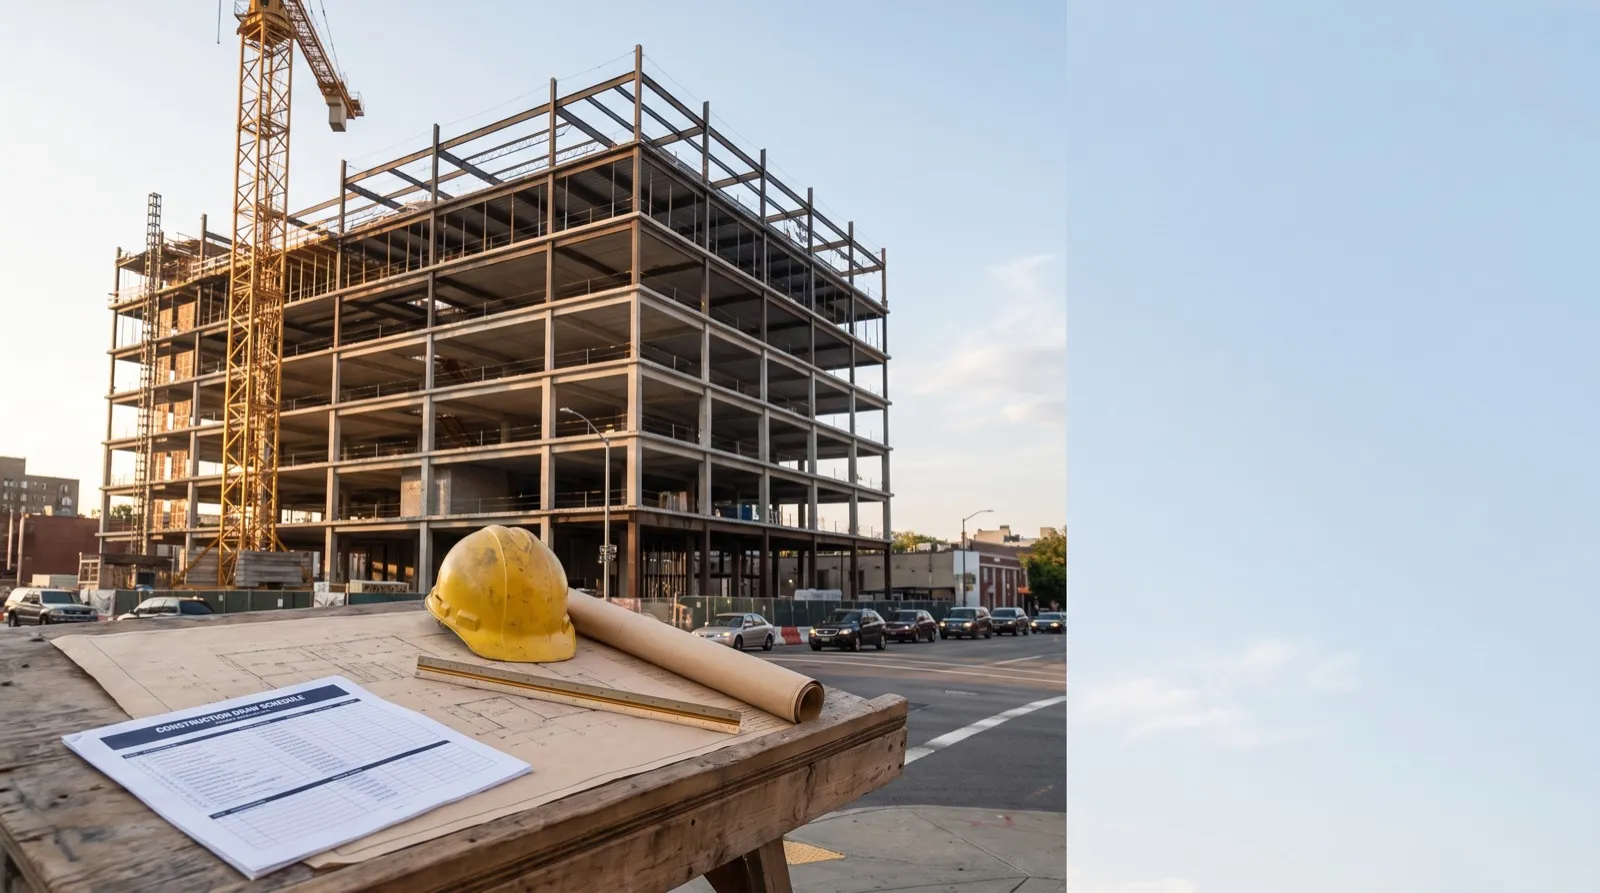
How a commercial real estate construction loan works: draw schedules, the interest reserve, LTC vs LTV, the perm take-out, and the SBA 504 construction path.
Commercial real estate loan qualifications come down to DSCR, LTV, debt yield, and your personal balance sheet. Here is exactly what lenders check.
DSCR loan pros and cons for investors: qualify on rent instead of income and skip the 10-property cap, but pay 20–25% down, a higher rate, and a prepay penalty.
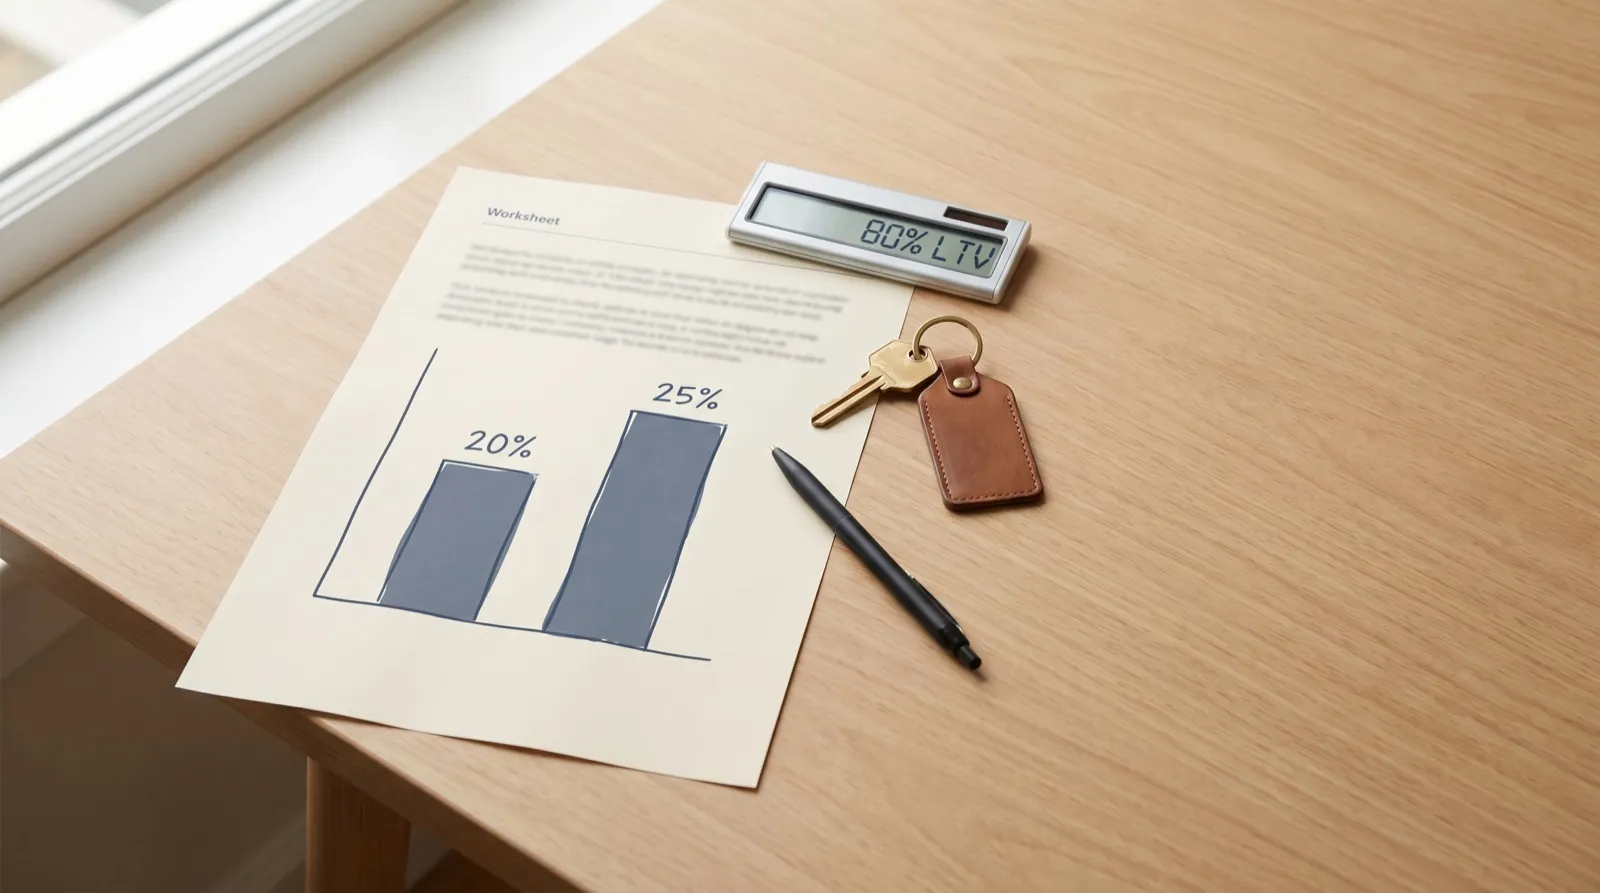
A DSCR loan down payment usually runs 20–25% (75–80% LTV), but your DSCR ratio, credit score, and property type move it. The 2026 breakdown, by scenario.
A DSCR loan for investment property qualifies on the rental's cash flow instead of your income, so you can scale past the conventional 10-property wall.
Commercial real estate loan terms cover term length, amortization, LTV, DSCR, recourse, and rate. What each one means before you sign.
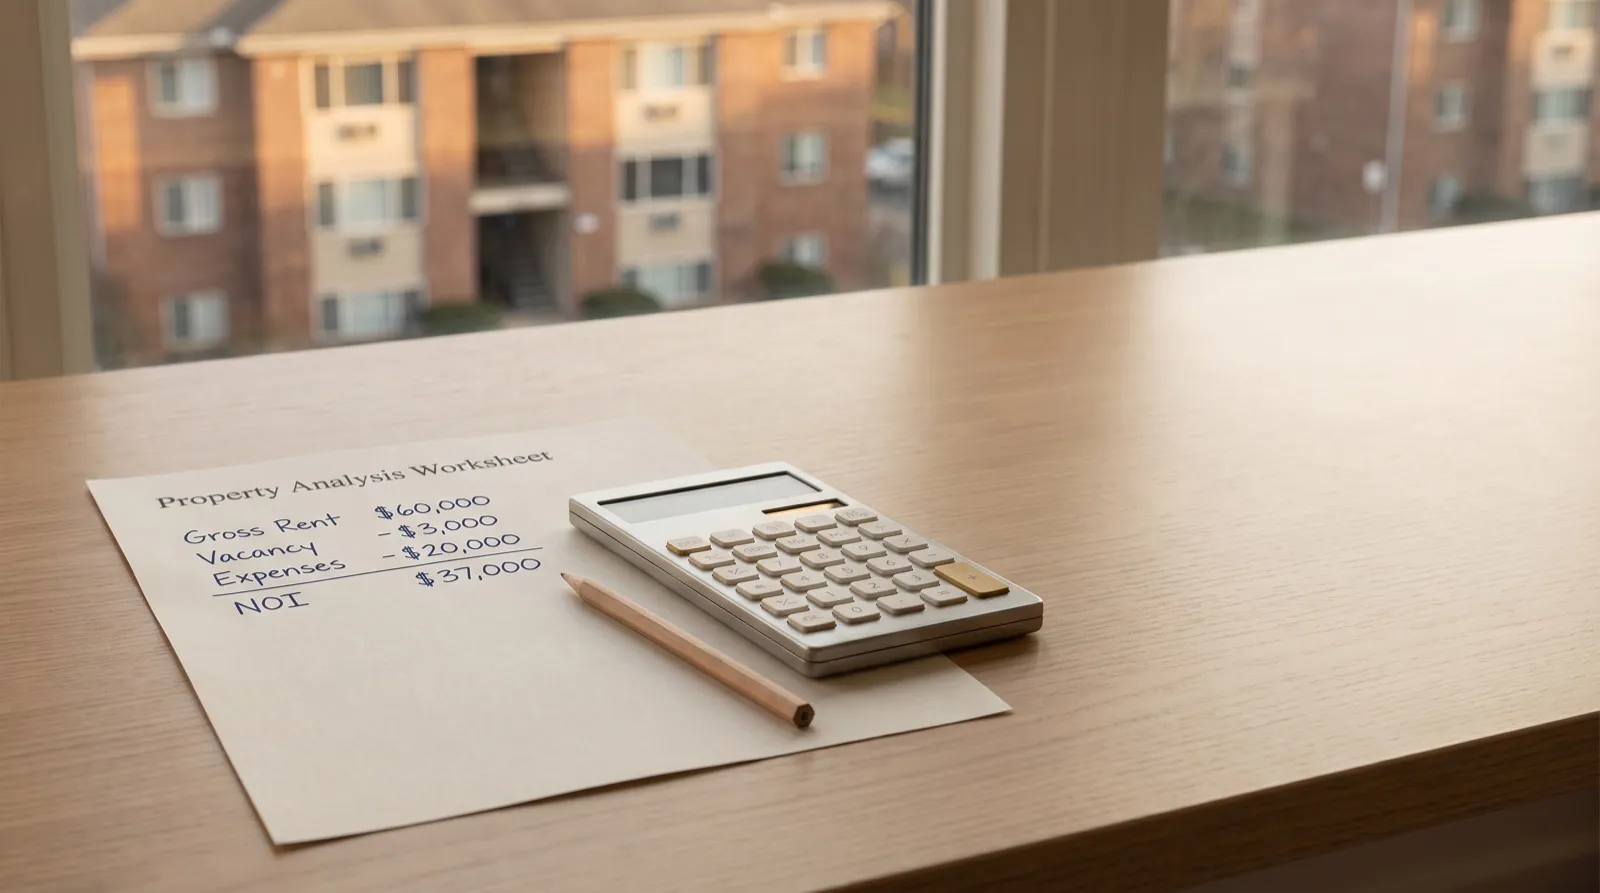
How to calculate DSCR step by step: build NOI, total your annual debt service, divide, and reverse the formula to find the maximum loan your property supports.
A DSCR loan qualifies you on your rental property's cash flow, not your personal income or tax returns. How the ratio works, and what lenders want.
A DSCR loan qualifies the property; a personal-income mortgage qualifies you. What each one asks for, what it costs, and when to choose which.
DSCR loan requirements in 2026: the minimum ratio, FICO, down payment, and reserves most lenders set, plus the borderline cases that still get funded.
Free for 7 days. No credit card.
Questions about your statement? I can help.
Connect your banks and export the PDF your lender needs. About 8 minutes the first time.
Start my free trial7 days free · No credit card required