SBA Lending
New SBA Rules Oct. 1, 2026: SOP 50 10 8.1 Explained
SBA SOP 50 10 8.1 starts October 1, 2026. The new SBA rules for buyers: 1.25x coverage on real earnings, a firm 10% for new owners, a 90-day Form 413, new fees.
Guides, updates, and best practices for SBA 7(a), 504, and Form 413 personal financial statements. Built for borrowers, brokers, and SBA-preferred lenders.
SBA SOP 50 10 8.1 starts October 1, 2026. The new SBA rules for buyers: 1.25x coverage on real earnings, a firm 10% for new owners, a 90-day Form 413, new fees.
SBA disaster loans are not forgiven. The relief SBA does offer, what a charge-off means for your balance, and what happens once Treasury has the debt.
A 7(a) loan prepayment penalty applies only above a 15-year maturity, and a 504 carries a separate debenture premium. What each one actually costs.
What happens if you default on an SBA loan: the lender accelerates, SBA honors its guaranty to the bank, and the unpaid balance follows you to Treasury.
Seller financing for a business can cover half your SBA equity injection, but only if the note sits on full standby for the life of the loan.
IRS Form 4506-C lets your lender pull your tax transcripts through IVES. What it authorizes, what the lender sees, and the 120-day clock that kills deals.
SBA Form 159 discloses what your broker or packager is paid on a 7(a) or 504 loan. Who counts as an agent, who signs, and which fees the SBA prohibits.
SBA Form 1919 is the borrower information form every 7(a) applicant signs. What each field and question asks, and the 2026 eligibility changes to know.
The 10 types of SBA loans in 2026: 7(a), 504, Express, WCP, CAPLines, MARC, export, microloan, and disaster, with amounts, terms, and Form 413 rules.
The benefits of an SBA loan include 10% down payments, 25-year terms, and capped rates. Weigh them against the fees and personal guarantee before you apply.
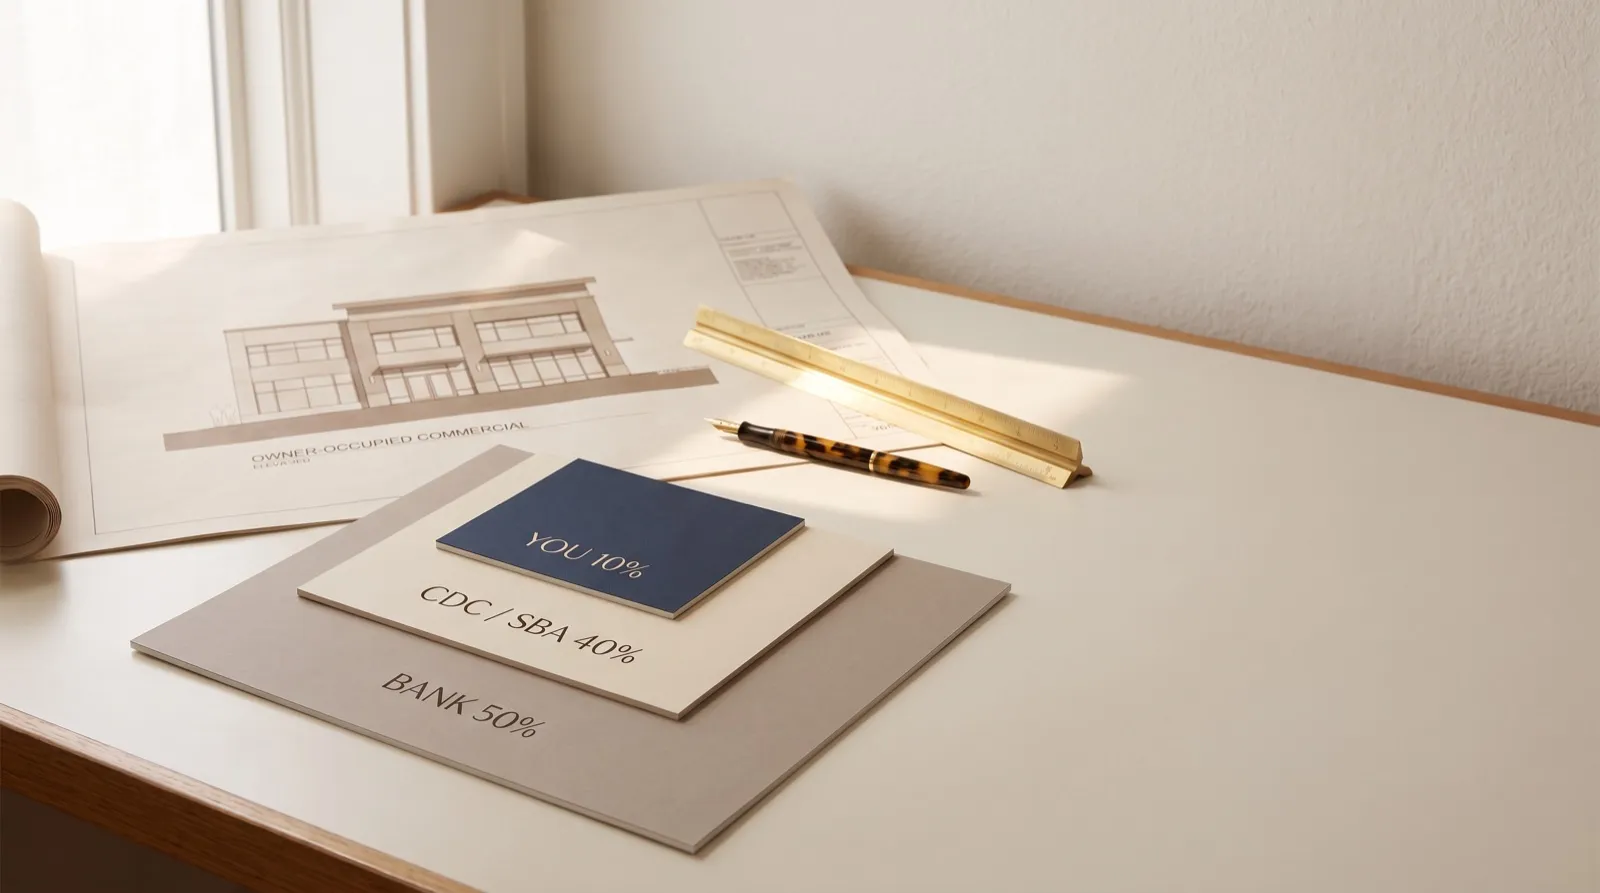
How an SBA 504 loan finances owner-occupied commercial real estate: the 50-40-10 stack, the fixed-rate CDC debenture, 25-year terms, and why it beats a 7(a).
SBA 504 loan requirements for 2026: the 50-40-10 structure, the 51% occupancy rule, the job-creation test that changed, and the Form 413 every owner files.
An SBA loan is a small-business loan the government partly guarantees. Covers the 7(a), 504, and microloan programs, 2026 rates, and the documents you prepare.
SBA 7(a) and 504 loans can't finance a passive rental property; the owner-occupancy rule blocks it. What qualifies instead, and the DSCR alternative.
SBA loan down payment rules in 2026: the 10% equity injection on 7(a) startups and business purchases, the 504 50/40/10 split, and which funds count.
SBA 7(a) loan requirements for 2026: eligibility, equity, credit, citizenship, the October 1 SOP 50 10 8.1 changes, and the Form 413 every owner files.
SBA 7(a) vs. 504 loan, compared for 2026: structure, rates, down payment, fees, and eligible uses, plus which program fits owner-occupied real estate.
Net worth for an SBA loan is total assets minus total liabilities on Form 413. How to calculate it, value each line, and what lenders do with it.
Personal financial statement signature requirements for SBA Form 413: who signs, when a spouse signs, the 90-day dating rule, and e-sign vs. wet ink.
SBA 504 personal guarantee requirements explained: who must sign an unlimited guaranty, how the bank and CDC differ, and when a guarantee can be limited.
The common SBA Form 413 mistakes that get a personal financial statement returned in underwriting, and how to fix each one before you submit.
Who must submit a personal financial statement (SBA Form 413) for a 7(a) loan, the 20% guaranty trigger, spousal rules, and what underwriters check.
On the current SBA Form 413, contingent liabilities sit beside Section 1, not in Section 5. What counts on each of the four lines.
SBA Form 413 is the personal financial statement every 20%+ owner of an SBA 7(a) or 504 borrower submits. How to fill out each section, line by line.
A real example of a completed SBA Form 413 for a hypothetical 7(a) applicant, with every line annotated — what underwriters see and why it matters.
Free for 7 days. No credit card.
Questions about your statement? I can help.
Connect your banks and export the PDF your lender needs. About 8 minutes the first time.
Start my free trial7 days free · No credit card required