How often you update a personal financial statement depends entirely on who is reading it. If a lender is underwriting you right now, the cadence is fixed. On a 7(a) or 504 loan, SBA Form 413 must be dated within 90 days of the day you submit it, and a slow underwrite can force a second signature before closing. If no one is underwriting you this quarter, treat once a year as the floor and update immediately after anything that moves a large number: a property sale, a new mortgage, a divorce, an inheritance.
Key takeaways
- A personal financial statement is a point-in-time snapshot tied to an “as of” date, so it starts aging the moment you sign it.
- For an SBA 7(a) or 504 application, the 90-day clock runs from your submission date, not from the day you signed the form.
- The form’s own instructions tell WOSB and 8(a) filers to update “as changes arise, but at least annually”, the cadence the rest of the lending world treats as an unwritten norm.
- Specific life events (sale, purchase, new debt, divorce, inheritance, a new guarantee) reset the clock regardless of when you last updated.
- Updating is not the same as starting over: you refresh the balances that moved and re-anchor the “as of” date.
How often should you update a personal financial statement?
There are three cadences, and the right one depends on what the statement is for.
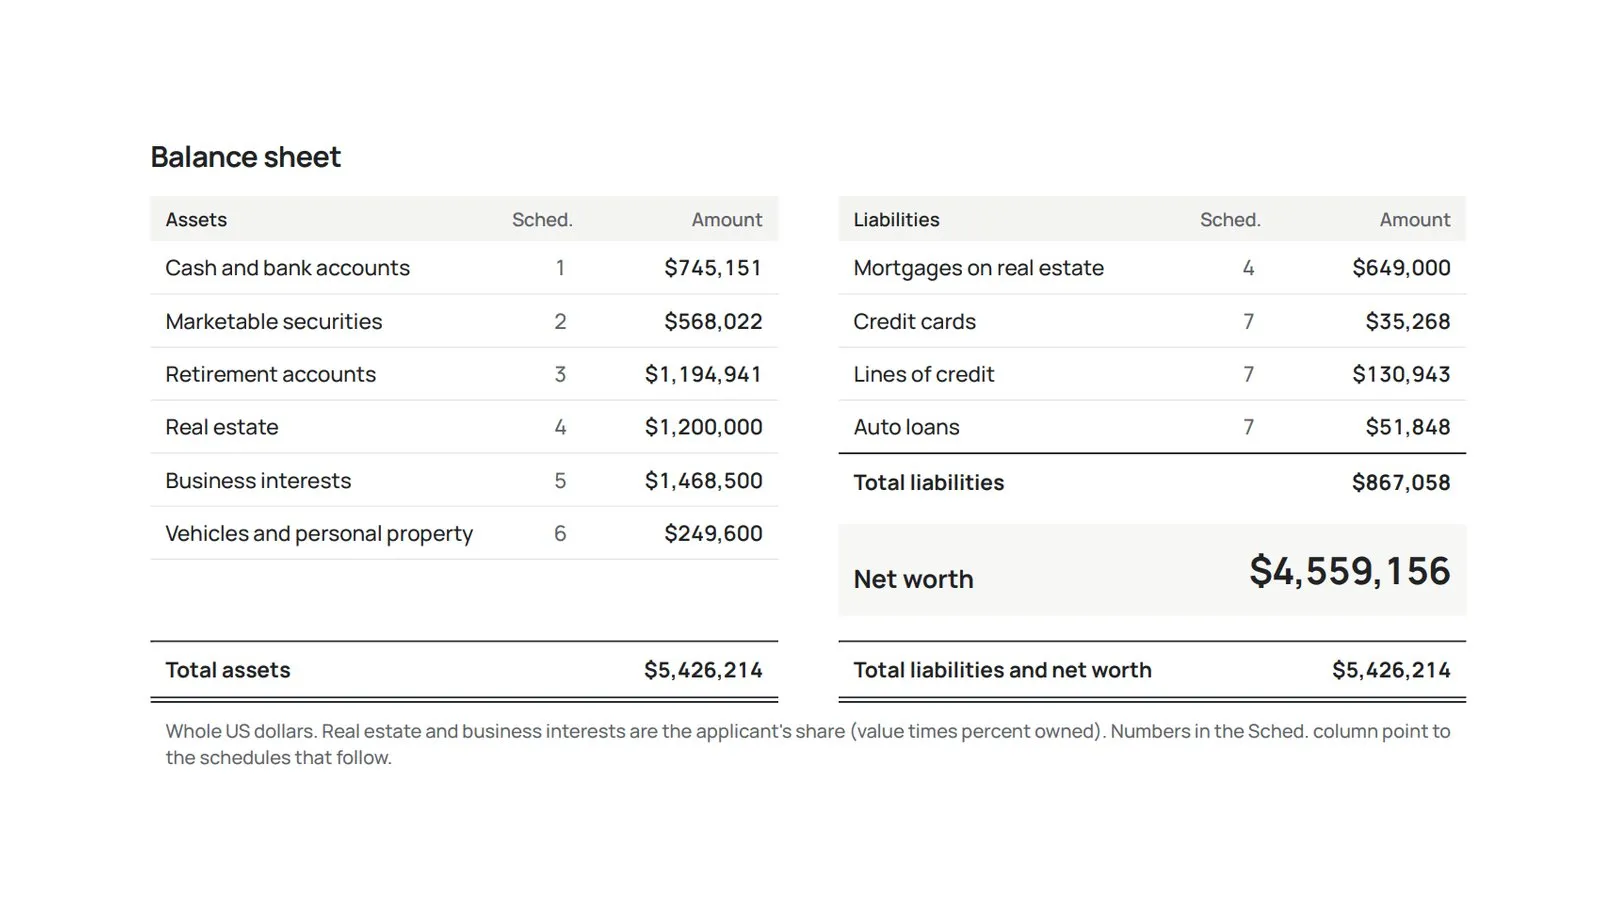
is a point-in-time snapshot of everything you own and everything you owe, measured as of a single date written at the top. Because it is anchored to that “as of” date, it begins going out of date the moment you sign it: every balance that moves afterward — a brokerage account, a mortgage payoff, a home’s market value — pulls the statement away from your actual position.
The first cadence is application-driven. When a lender is underwriting you, the freshness window is set for you, and for SBA loans it is written on the form itself. The second is the annual baseline: the once-a-year refresh that keeps the document useful for whoever asks next, whether that is a bank, a commercial landlord, or your own year-end review. The third is event-driven: certain changes are large enough that they invalidate the statement no matter how recently you updated it.
Here is the whole answer in one view:
| Your situation | How current the statement must be | Who sets it |
|---|---|---|
| Active SBA 7(a) or 504 application | Within 90 days of submission | SOP 50 10 8.1, from October 1, 2026 (the form still prints 120) |
| Active SBA Disaster loan application | Within 90 days of submission | SBA Form 413 |
| Stricter SBA-preferred lenders | Often within 60 days | The lender’s internal policy |
| Existing loan with a reporting covenant | Annually, usually within 90–120 days of fiscal year-end | Your loan agreement |
| No active application | At least once a year | Planning practice (and the Form 413 instructions, for WOSB/8(a) filers) |
| After a trigger event | Immediately | The event itself |
The mistake worth avoiding is treating these as one cadence. A statement that satisfies an SBA underwriter today can be stale for a different lender six months from now, and a statement you refreshed in January is wrong the day you close on a rental property in March. The American Institute of CPAs frames a personal financial statement as a presentation of assets and liabilities as of a specified date. The “as of” language is the whole reason the cadence question exists.
The 90-day rule for SBA loans (and why the form still says 120)
If you are applying for an SBA loan, you do not have to guess. The current SBA Form 413 prints the requirement directly above the assets grid, next to the “as of” date field:
This information is current as of (mm/dd/yyyy) — must be within 90 days of submission for Disaster or within 120 days of submission for 7(a)/504/SBG/8(a) BD/WOSB.
That line predates SOP 50 10 8.1. For 7(a) and 504 loans submitted to SBA on or after October 1, 2026, the SOP tells lenders the owner financial statement must be “signed and dated within 90 days of submission to SBA.” Its guaranty section also asks for a personal financial statement from each guarantor “dated within 90 days of loan approval.” Until SBA reissues the form, the printed 120 days still describes surety bond, 8(a), and WOSB filings. On a 7(a) or 504 file, work to 90.
Two details get missed. First, the clock runs from the date of submission, not from the date you signed the form. A statement signed on March 1 and submitted on March 20 has used 19 of its 90 days before underwriting even begins. Second, the window is an SBA requirement that applies regardless of which lender processes the file, though many SBA-preferred lenders layer a stricter internal window on top of it, commonly 60 days. The full line-by-line treatment of the form lives in the section-by-section Form 413 walkthrough and the SBA Form 413 guide.
There is a closing-side wrinkle too. If your application stalls and the window lapses before the loan funds, the lender asks for an updated Form 413. For 504 loans specifically, SBA SOP 50 10 8 (effective June 1, 2025) requires the borrower to certify that there has been no unremedied substantial adverse change in their financial condition since application, and to furnish current interim financial statements at closing. A stale personal financial statement gets refreshed as a matter of course.
Every owner with 20% or greater ownership must complete a Personal Financial Statement with full supporting documentation. This includes account statements, retirement account summaries, real estate documentation, and listed liabilities. Getting these materials current and organized early helps avoid unnecessary delays later.
The annual refresh: the baseline everyone should keep
Outside of an active application, once a year is the floor. The SBA wrote that cadence into the form’s own instructions. In the section for Women-Owned Small Business and 8(a) Business Development applicants, the form directs each filer claiming economic disadvantage to update it “as changes arise, but at least annually, to ensure the information is current, accurate and complete.” That is the agency putting in writing the rhythm the rest of the lending world treats as an unwritten standard.
For borrowers who already have an SBA or commercial loan, the annual refresh is usually contractual. Loan agreements commonly include a reporting covenant requiring updated personal financial statements within 90 to 120 days after the borrower’s fiscal or calendar year-end, mirroring the deadline for the business financial statements. Missing that deadline is a covenant issue in its own right; lenders treat a deteriorating or missing financial picture as seriously as a late payment, because the first usually precedes the second.
Even with no loan in the picture, an annual pass earns its keep. It is the cheapest time to catch a number you would otherwise scramble to verify under a lender’s deadline, and it gives you a clean prior-year comparison. You can run the math in the free net-worth calculator and keep the result as your yearly anchor, or start from a personal financial statement template and roll it forward each January.
Trigger events that reset the clock
Some changes are large enough to invalidate a statement on the day they happen, regardless of when you last updated. These are the events that, in practice, generate the most underwriter callbacks when they are missing, because the lender pulls a current credit report and sees the new mortgage or the released guarantee that your statement does not reflect.
- Buying or selling real estate. A property purchase adds an asset and a mortgage; a sale removes both and converts the equity to cash. Real estate is the largest line on most statements, so either move is material.
- Selling a business or a business interest. This changes your income source, your asset mix, and often your liquidity in a single transaction.
- Taking on significant new debt. A new mortgage, equipment loan, or large personal loan changes both the liabilities column and your monthly obligations.
- Signing a new personal guarantee. A guarantee is a contingent liability. A new one consumes part of your borrowing capacity; a released one frees it back up. Both belong on an updated statement.
- Marriage or divorce. Either event restructures asset ownership, joint accounts, and beneficiary designations. A divorce in particular can change nearly every line.
- A large inheritance or gift. Once an estate settles and assets transfer, your net worth and liquidity can jump enough that the prior statement understates you.
- Paying off a major debt. Retiring a mortgage or business loan is a positive change worth reflecting promptly, especially before you next apply for credit.
- A large swing in an investment account. A concentrated position or a sharp market move can shift net worth meaningfully inside a single quarter.
The pattern behind the list: if a change would move your total assets, total liabilities, or net worth by a margin a lender would notice, refresh the statement rather than waiting for the annual cycle. For situational guidance keyed to a specific filing, the business loan applications use case walks through what a lender expects to see when one of these events is part of your story.
Why a personal financial statement goes stale faster than you think
The case for a regular refresh is not abstract. Household balance sheets move a lot, and they move most in exactly the lines that dominate a personal financial statement.
37%
Real (inflation-adjusted) increase in median U.S. family net worth from 2019 to 2022, the largest three-year jump in the modern Survey of Consumer Finances, which has run since 1989.
A statement that was accurate at the start of that window understated the median family by more than a third by the end of it. The driver was concentrated in home equity, the single biggest line on most statements:
$139,100 → $201,000
Median net housing value (home value minus mortgage debt) for U.S. homeowners, 2019 vs. 2022. Home equity is the largest asset on most personal financial statements, and it moved about 44% in three years.
Those are three-year figures, but the same forces operate inside the SBA’s 90-day window. A brokerage account reprices daily, a mortgage amortizes monthly, and a home’s market value can shift a full quarter’s worth between the day you sign and the day an underwriter opens the file. That is the mechanical reason the SBA caps the form’s age at 90 days on 7(a) and 504 loans and the form’s instructions ask for an update “as changes arise.” The snapshot is only as good as the day it was taken.
Build your personal financial statement in minutes
StatementsReady syncs bank balances read-only through Plaid, fills SBA Form 413, and exports a lender-ready PDF on demand.
- SBA Form 413 with every section filled
- Bank sync through Plaid, read-only
- 7 days free, no card
What “updating” actually means (you are not starting over)
The word “update” makes this sound heavier than it is. You are not rebuilding the statement from scratch; you are re-anchoring it to a new “as of” date and refreshing the lines that actually moved.
A practical refresh is four steps:
- Set a new “as of” date and choose it to line up with your most recent month-end statements, so the supporting documents reconcile cleanly.
- Re-pull the volatile lines: cash balances, brokerage and retirement account values, current mortgage and loan balances, and a current market value for any real estate.
- Re-check contingent liabilities: add any new personal guarantee or co-signed obligation, and remove any that were released.
- Re-total and confirm that assets minus liabilities still reconciles to net worth.
This is where the tooling matters. In a spreadsheet, each refresh means re-keying every figure and hoping the totals still tie. With software that already holds last quarter’s statement, rolling it forward to a new date is a matter of updating the balances that changed and regenerating the document; the structure carries over. The trade-offs between the two approaches are laid out in the software-versus-Excel comparison. The faster the refresh, the more likely you are to actually do it on the cadence your situation calls for, instead of scrambling when a lender sets a deadline.
For more on the document itself and where it fits, see the personal financial statement versus balance sheet breakdown and the rest of the personal finance archive.
Skip the spreadsheet
A lender-ready personal financial statement from synced balances, in about 8 minutes.
- 7 days free
- No credit card
- PDF, SBA Form 413, Word, or Excel
Build your personal financial statement in minutes
StatementsReady syncs bank balances read-only through Plaid, fills SBA Form 413, and exports a lender-ready PDF on demand.
- SBA Form 413 with every section filled
- Bank sync through Plaid, read-only
- 7 days free, no card